Price to Sales Ratio (P/S): Formula, Meaning & Calculation
Price-to-Sales (P/S) Ratio: Formula, Meaning, Calculation, Examples & How to Use It
The Price to Sales ratio (P/S) is one of the simplest valuation metrics used in stock analysis. It compares a company’s market value with the revenue or sales it generates.
In simple terms, the P/S ratio answers this question:
How much are investors paying for every ₹1 of a company’s sales?
For example, if a company has a P/S ratio of 3×, the market is valuing its equity at approximately ₹3 for every ₹1 of annual revenue.
But there is an important catch: a low P/S ratio does not automatically mean a stock is cheap, and a high P/S ratio does not automatically mean it is expensive.
Revenue is only the starting point. Profit margins, growth, debt, cash flow, industry economics and future expectations can dramatically change how a P/S ratio should be interpreted. The CFA Institute similarly identifies profitability, growth and required return as fundamental drivers of justified P/S multiples.
This guide explains the P/S ratio from the basics through more advanced valuation concepts, including how to use it when analyzing stocks.
Table of Contents
What Is the Price-to-Sales (P/S) Ratio?
The Price-to-Sales ratio, commonly abbreviated as P/S ratio, is a valuation multiple that compares a company’s market capitalization with its revenue over a specified period.
The standard formula is:
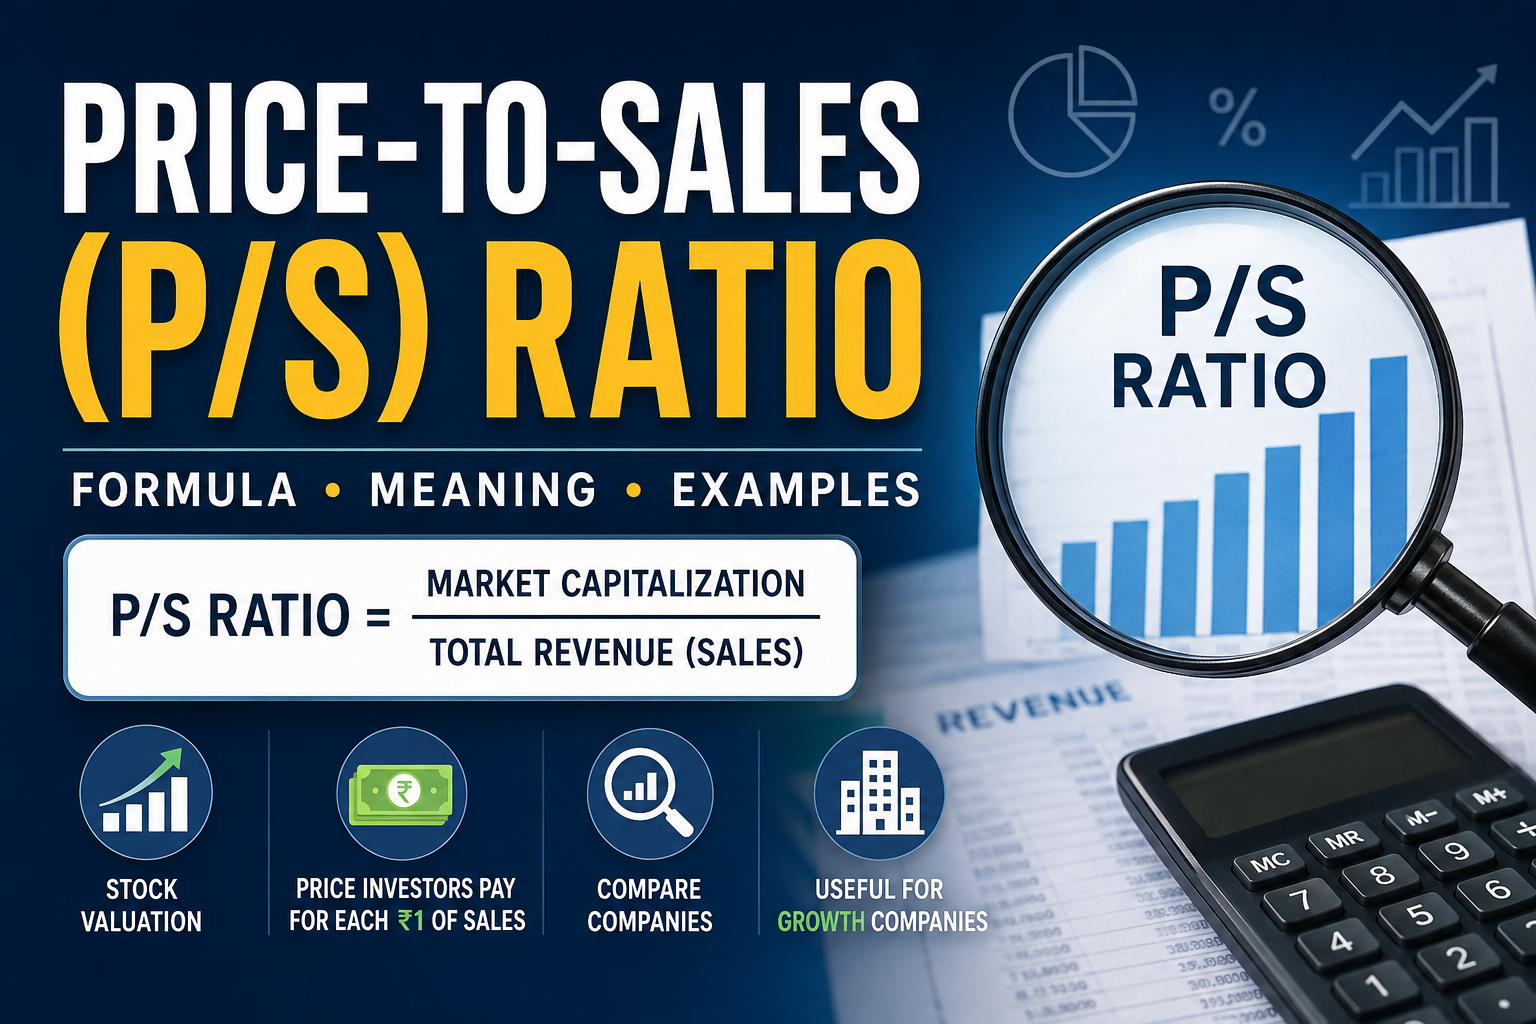
P/S Ratio = Market Capitalization ÷ Revenue
It can also be calculated on a per-share basis:
P/S Ratio = Share Price ÷ Revenue Per Share
Both approaches produce the same result when the figures use the same share count and reporting period. (Corporate Finance Institute)
P/S Ratio in Simple Words
Imagine a company generates ₹100 crore in annual revenue and the stock market values the company’s equity at ₹300 crore.
Therefore:
P/S = ₹300 crore ÷ ₹100 crore = 3×
A P/S of 3× means investors are valuing the company’s equity at ₹3 for every ₹1 of annual sales.
Notice the wording carefully: sales, not profit.
That distinction is the key to understanding both the usefulness and the limitations of this ratio.
What Does the P/S Ratio Actually Tell You?
P/S tells you how much the market is willing to pay relative to a company’s revenue.
It does not directly tell you:
- how profitable the company is;
- how much cash it generates;
- how much debt it has;
- whether revenue is growing sustainably;
- whether management allocates capital effectively; or
- whether the stock will generate a positive return.
Therefore, P/S should generally be treated as a relative valuation tool, rather than a complete measure of business quality.
Price-to-Sales Ratio Formula
There are two commonly used versions of the P/S formula.
Market Capitalization Formula
P/S Ratio = Market Capitalization ÷ Total Revenue
Where:
Market Capitalization = Current Share Price × Shares Outstanding
For example:
- Share price = ₹200
- Shares outstanding = 10 crore
- Market capitalization = ₹2,000 crore
- Annual revenue = ₹500 crore
Therefore:
P/S = ₹2,000 crore ÷ ₹500 crore = 4×
Per-Share Formula
You can also calculate P/S using:
P/S Ratio = Share Price ÷ Revenue Per Share
Revenue per share is:
Revenue Per Share = Total Revenue ÷ Shares Outstanding
Using the same example:
Revenue per share = ₹500 crore ÷ 10 crore = ₹50
Then:
P/S = ₹200 ÷ ₹50 = 4×
The result is identical.
This per-share approach is commonly used in stock-market education, including Indian valuation examples. (Zerodha)
How to Calculate the P/S Ratio Step by Step
Calculating P/S is straightforward, but choosing the correct numbers is more important than the arithmetic.
Step 1: Find the Company’s Market Capitalization
Market capitalization represents the market value of the company’s outstanding equity.
You can calculate it as:
Market Cap = Share Price × Shares Outstanding
For listed companies, market capitalization is also commonly available through stock exchanges and financial-data platforms.
Step 2: Find the Company’s Revenue
Next, find the company’s revenue for the period you’re analyzing.
For a listed company, revenue can be found in its financial statements, annual reports and quarterly results.
For an Indian company, pay particular attention to terms such as revenue from operations, sales, and total income. These figures are not always interchangeable.
Step 3: Divide Market Capitalization by Revenue
Suppose:
- Market capitalization = ₹10,000 crore
- TTM revenue = ₹2,000 crore
Then:
P/S = ₹10,000 crore ÷ ₹2,000 crore = 5×
The market is therefore valuing the company’s equity at ₹5 for every ₹1 of trailing revenue.
Step 4: Check the Reporting Period
This step is frequently overlooked.
If today’s market capitalization is divided by revenue from an old financial year, the resulting ratio may not represent the company’s current valuation accurately.
For many analyses, investors use TTM (Trailing Twelve Months) revenue because it incorporates the most recent four quarters of reported financial information.
P/S Ratio Example: A Simple Calculation
Consider a fictional company called ABC Technologies Ltd.
Suppose:
- Market capitalization = ₹1,000 crore
- TTM revenue = ₹250 crore
The calculation is:
P/S = ₹1,000 crore ÷ ₹250 crore
P/S = 4×
What does this mean?
The market is valuing ABC Technologies at ₹4 for every ₹1 of annual revenue.
It does not mean:
- the company earns ₹4 profit for every ₹1 invested;
- the company will generate ₹4 of profit in the future;
- the stock is automatically expensive; or
- the stock is automatically worth buying.
The P/S ratio only describes the relationship between market value and revenue.
The rest of the analysis comes afterward.
What Is a Good P/S Ratio?
There is no universally good P/S ratio.
A P/S of 1× might be expensive for one business and cheap for another. Similarly, a P/S of 10× could be unreasonable for a low-margin business but potentially understandable for a high-growth, high-margin business.
P/S ratios vary significantly across industries, which is why meaningful comparisons generally require comparable companies. (Wall Street Prep)
Is a Low P/S Ratio Always Better?
No.
Suppose Company A has:
- P/S = 0.8×
- Revenue growth = -10%
- Net margin = 1%
- High debt
A low P/S could simply reflect the market’s concerns about the company’s future.
The company may look inexpensive relative to revenue because investors expect revenue, profitability or cash flow to deteriorate.
A low multiple can therefore represent low expectations, not necessarily an opportunity.
Is a High P/S Ratio Always Bad?
Again, no.
Imagine another company with:
- P/S = 8×
- Revenue growth = 30%
- Net margin = 25%
- Strong balance sheet
- Recurring revenue
Investors may be willing to pay a higher multiple because they expect the company to generate significantly more revenue and profit in the future.
The important question isn’t simply:
“Is P/S high?”
Instead ask:
“What business quality and future growth expectations are embedded in this P/S ratio?”
Why Industry Comparison Matters
A supermarket, software company and pharmaceutical manufacturer can have completely different economics.
For example, a supermarket might generate enormous revenue but operate on thin margins, while a software company may generate less revenue but retain a much larger percentage as operating or net profit.
Therefore, comparing their P/S ratios without considering their business models can produce misleading conclusions.
How to Interpret a P/S Ratio
The easiest way to understand P/S is to interpret what investors are paying for each unit of revenue.
What Does a P/S Below 1 Mean?
A P/S below 1× means the company’s market capitalization is less than one year’s revenue.
For example:
- Market cap = ₹800 crore
- Revenue = ₹1,000 crore
P/S = 0.8×
That means the market values the company’s equity at ₹0.80 for every ₹1 of annual revenue.
But this does not prove undervaluation.
The business might have:
- declining revenue;
- very low margins;
- heavy debt;
- significant capital requirements;
- poor cash generation; or
- serious competitive problems.
What Does a P/S of 1 Mean?
A P/S of 1× means:
Market capitalization = annual revenue
In simplified terms, the market is assigning ₹1 of equity value for every ₹1 of annual sales.
Again, this is a mathematical relationship, not a verdict on valuation.
What Does a P/S of 5 Mean?
A P/S of 5× means investors are valuing the company at approximately ₹5 for every ₹1 of annual revenue.
Whether that is reasonable depends on what investors expect the business to accomplish in the future.
What Does a Very High P/S Mean?
A very high P/S generally means the market is assigning a substantial valuation relative to current revenue.
That can happen because investors expect:
- rapid revenue growth;
- improving margins;
- strong competitive advantages;
- recurring revenue;
- significant future cash flows; or
- continued investor demand.
But high expectations also create risk.
If the expected growth fails to materialize, the valuation multiple can contract even if revenue continues to increase.
P/S Ratio and Profit Margins: The Missing Piece
This is arguably the most important concept when interpreting P/S.
Revenue is not profit.
Consider two companies:
| Metric | Company A | Company B |
|---|---|---|
| Revenue | ₹1,000 Cr | ₹1,000 Cr |
| Market Cap | ₹3,000 Cr | ₹3,000 Cr |
| P/S | 3× | 3× |
| Net Margin | 2% | 20% |
| Net Profit | ₹20 Cr | ₹200 Cr |
Both companies have exactly the same P/S ratio.
But Company B generates 10 times as much net profit from the same revenue.
This demonstrates why P/S cannot be interpreted independently of profitability.
Why Revenue Alone Is Not Enough
Suppose two companies each generate ₹1,000 crore of revenue.
Company A keeps ₹200 crore as net profit.
Company B keeps only ₹20 crore.
If both have the same market capitalization, their P/S ratios will be identical.
But the economic value of their revenue is clearly different.
This is why the CFA Institute identifies profit margin, growth and required return as fundamental drivers of a justified P/S multiple. (CFA Institute)
The Relationship Between P/S and P/E
Under consistent definitions and assumptions, there is a useful conceptual relationship:
P/E ≈ P/S ÷ Net Profit Margin
For example, suppose:
- P/S = 4×
- Net profit margin = 10%
Then:
Approximate P/E = 4 ÷ 0.10 = 40×
Why?
Because if a company turns ₹100 of revenue into ₹10 of profit, then revenue is ten times profit.
This is not a substitute for calculating the actual P/E ratio, but it illustrates why margin matters enormously when interpreting P/S.
A high-margin business can justify a higher P/S than a low-margin business because more of its revenue can ultimately become earnings and cash flow.
Why Investors Use the P/S Ratio
Despite its limitations, P/S can be extremely useful.
Useful When a Company Has Negative Earnings
P/E becomes difficult to interpret when a company has negative earnings.
For example, if a company loses ₹10 per share, a conventional P/E calculation doesn’t provide the usual meaningful positive multiple investors expect.
P/S can still be calculated because revenue can remain positive even when profit is negative.
This is one of the major reasons P/S is used for young or loss-making companies. (Corporate Finance Institute)
Revenue Can Be More Stable Than Earnings
Profit can fluctuate because of:
- one-time expenses;
- restructuring charges;
- depreciation;
- write-offs;
- interest costs; and
- other accounting or financial factors.
Revenue is not immune to accounting effects, but it can provide a different and sometimes more stable perspective on the underlying scale of a business.
The CFA Institute notes that sales are generally more stable than earnings and are not negative. (CFA Institute)
Useful for Early-Stage Growth Companies
Some growth companies invest heavily in expansion before producing substantial profits.
P/S can help investors assess how much the market is paying for current revenue while considering whether future growth could eventually lead to sustainable profitability.
However, growth alone does not justify an unlimited valuation.
Useful for Comparing Similar Businesses
P/S becomes most useful when comparing companies with similar:
- business models;
- industries;
- growth rates;
- margins;
- capital requirements; and
- financial structures.
Limitations and Disadvantages of the P/S Ratio
P/S is simple precisely because it ignores many things.
That simplicity is both its strength and its weakness.
P/S Ignores Profitability
The ratio doesn’t tell you whether the company earns a profit from its revenue.
A company generating ₹1,000 crore in sales with a 1% margin is economically very different from one generating the same sales with a 20% margin.
P/S Ignores Debt
Two companies can have the same market capitalization and revenue but very different debt levels.
P/S doesn’t directly capture that difference.
A heavily indebted company can therefore appear attractive on a P/S basis even though its financial risk is considerably higher.
This is one reason analysts may also examine EV/Sales, which incorporates capital structure. (Wall Street Prep)
P/S Ignores Cash Flow
A company can report substantial revenue without converting all of that revenue into cash immediately.
Working-capital requirements, receivables, inventory and capital expenditure can materially affect cash generation.
Therefore, revenue growth should eventually be checked against operating cash flow and free cash flow.
Revenue Quality Matters
Not all revenue is equally valuable.
Consider the difference between:
- recurring subscription revenue;
- one-time project revenue;
- acquisition-driven revenue;
- revenue generated through aggressive discounting; and
- revenue that requires substantial working capital.
Two businesses with identical revenue and P/S ratios can have very different revenue quality.
Revenue Recognition Can Affect Comparability
Revenue is an accounting measure, and differences in revenue recognition practices can affect when sales are recorded.
That doesn’t mean revenue is inherently unreliable. It means investors should understand the accounting context before assuming that two companies’ reported revenue figures are perfectly comparable.
The CFA Institute specifically highlights revenue recognition as one of the issues that can affect P/S analysis. (CFA Institute)
P/S Can Be Misleading During Rapid Growth
A company growing at 50% annually may trade at a much higher P/S than a mature company growing at 5%.
That doesn’t automatically make the growth company overvalued.
But it does mean the valuation may depend heavily on future growth continuing.
If growth slows sharply, the market may reduce the multiple.
P/S Ratio vs. P/E Ratio
P/S and P/E answer different valuation questions.
| Feature | P/S Ratio | P/E Ratio |
|---|---|---|
| Denominator | Revenue | Net income |
| Measures | Value relative to sales | Value relative to earnings |
| Works with loss-making companies | Generally yes | Generally not meaningful |
| Considers profitability | No | Yes |
| Useful for growth companies | Often | Depends on profitability |
| Main weakness | Ignores margins | Can be distorted by earnings fluctuations |
Is P/S Better Than P/E?
Neither is universally better.
P/S can be particularly useful when earnings are negative or unusually volatile.
P/E becomes especially informative when a company has established, reasonably representative profitability.
For a mature profitable company, relying only on P/S while ignoring earnings would leave out an important part of the valuation picture.
A sensible analysis may therefore use P/S, P/E, margins, cash flow and balance-sheet metrics together rather than trying to identify one universally superior ratio.
P/S Ratio vs. EV/Sales
Another important comparison is P/S versus EV/Sales.
What Is EV/Sales?
The formula is:
EV/Sales = Enterprise Value ÷ Revenue
Enterprise value broadly reflects the value of the operating business available to all capital providers and incorporates debt and cash in its calculation.
Key Difference Between P/S and EV/Sales
P/S uses:
Market Capitalization ÷ Revenue
EV/Sales uses:
Enterprise Value ÷ Revenue
The difference becomes important when companies have substantially different amounts of debt and cash.
For example, imagine two companies have:
- identical revenue;
- identical market capitalization; but
- dramatically different debt.
Their P/S ratios could be identical even though their enterprise values are very different.
EV/Sales can therefore provide a more useful comparison when capital structures differ. The CFA Institute describes EV/Sales as conceptually preferable for comparisons among companies with varying capital structures.
When Is EV/Sales More Useful?
EV/Sales is particularly worth considering when comparing companies with significantly different:
- debt levels;
- cash balances;
- capital structures; or
- financing arrangements.
But EV/Sales also has a major limitation: it still doesn’t tell you directly how profitable the revenue is.
Trailing vs. Forward P/S Ratio
Not all P/S ratios use the same revenue period.
What Is Trailing P/S?
A trailing P/S uses historical revenue, often TTM revenue.
TTM means Trailing Twelve Months.
For example, instead of using only the previous financial year’s revenue, an analyst might use the latest four reported quarters.
The benefit is that the denominator is based on actual reported results.
What Is Forward P/S?
A forward P/S uses estimated future revenue.
For example:
Forward P/S = Current Market Capitalization ÷ Expected Next-12-Month Revenue
The advantage is that valuation is being considered relative to expected future business activity.
The disadvantage is obvious:
the forecast may be wrong.
If analysts expect revenue of ₹1,000 crore and actual revenue turns out to be ₹700 crore, the forward P/S calculation changes materially.
Which Should Investors Use?
There isn’t one universally correct answer.
Trailing P/S provides a valuation based on reported historical performance.
Forward P/S incorporates expectations about the future.
For serious analysis, it can be useful to look at both, while remembering that estimates are not facts.
How to Use the P/S Ratio in Stock Analysis
P/S works best as part of a broader analytical process.
Step 1: Look at Revenue Growth
First ask:
Is revenue growing?
Then ask:
How fast?
A company with a 5× P/S and 5% growth is a very different proposition from a company with a 5× P/S and 30% growth.
But growth should also be evaluated for sustainability.
Step 2: Examine Profit Margins
Look at:
- gross margin;
- operating margin;
- EBITDA margin where appropriate; and
- net profit margin.
The objective is to understand how much of the company’s revenue eventually becomes profit.
Step 3: Check Cash Flow
Revenue and accounting profit aren’t the same as cash.
Examine:
- operating cash flow;
- free cash flow;
- capital expenditure; and
- working-capital changes.
A business that consistently converts revenue and profits into cash is fundamentally different from one that repeatedly consumes cash.
Step 4: Examine Debt
Check:
- total debt;
- net debt;
- interest expense;
- debt maturity; and
- interest coverage where relevant.
A low P/S ratio doesn’t eliminate balance-sheet risk.
Step 5: Compare With Peers
Compare the company with businesses that have similar economics.
Ideally consider:
P/S + revenue growth + margins + debt + cash flow
rather than P/S alone.
Step 6: Compare With Historical Valuation
Look at the company’s historical P/S range where reliable historical data is available.
Ask:
Is today’s P/S unusually high or low compared with the company’s own history?
Historical comparisons aren’t perfect because businesses change, but they can provide useful context.
Step 7: Ask What Growth Is Already Priced In
This is one of the most important questions for advanced investors.
Suppose a company trades at 10× sales.
Don’t simply ask:
“Is 10× high?”
Ask:
“What level of future revenue growth and profitability would make this valuation reasonable?”
That shifts the analysis from a simplistic ratio comparison toward actual valuation thinking.
P/S Ratio in Indian Stock Analysis
P/S can also be useful when analyzing Indian listed companies, but the same principles apply.
Where to Find Revenue Data for Indian Companies
For Indian companies, useful primary sources include:
- annual reports;
- quarterly financial results;
- investor presentations;
- stock-exchange disclosures; and
- company filings.
Whenever possible, use the company’s own financial statements rather than blindly relying on a third-party data platform.
TTM P/S vs. Annual P/S for Indian Stocks
Suppose a company has recently experienced rapid growth.
Using revenue from the previous financial year might make its current P/S appear higher or lower than a calculation using the latest four quarters.
TTM revenue can therefore provide a more current denominator.
However, for highly seasonal businesses, you should understand the company’s normal revenue cycle before interpreting the number.
Why Sector Comparison Matters in India
P/S ratios can differ substantially between industries such as:
- IT services;
- FMCG;
- automobiles;
- pharmaceuticals;
- manufacturing;
- consumer businesses;
- commodity companies; and
- technology businesses.
The underlying economics are different.
Therefore, a P/S comparison across unrelated sectors can be much less informative than comparing companies within the same industry.
Why P/S Is Not Usually the Primary Metric for Banks
Banks and many financial institutions have fundamentally different financial structures from industrial and consumer businesses.
For that reason, investors generally rely more heavily on metrics designed for financial companies, such as price-to-book, return on equity, asset quality and other banking-specific measures, rather than treating P/S as the primary valuation tool.
Common P/S Ratio Mistakes Investors Make
Mistake 1: Assuming Low P/S Means Undervalued
A low P/S can indicate that the market has low expectations for the business.
Always investigate why the multiple is low.
Mistake 2: Comparing Different Industries
A P/S of 2× doesn’t have the same meaning for every industry.
Compare companies with reasonably similar business economics.
Mistake 3: Ignoring Profit Margins
Revenue without profitability can be misleading.
Always examine margins alongside P/S.
Mistake 4: Using Outdated Revenue
A current market capitalization divided by revenue from several years ago can produce a misleading picture.
Check the period carefully.
Mistake 5: Ignoring Debt
P/S is an equity valuation multiple.
It doesn’t adequately capture the risk associated with different levels of leverage.
Mistake 6: Confusing Revenue With Profit
If a company generates ₹1,000 crore in revenue, that does not mean it earns ₹1,000 crore.
Expenses must be deducted before arriving at profit.
Mistake 7: Treating Forward Estimates as Facts
Forecast revenue is an estimate.
Actual results can be substantially different.
Mistake 8: Using P/S as a Standalone Buy/Sell Signal
A valuation multiple is an analytical input, not a trading signal.
Even a company that appears inexpensive can decline if its business fundamentals deteriorate or market expectations change.
A Practical P/S Ratio Checklist
Before interpreting a company’s P/S ratio, ask:
What revenue period am I using?
Is it annual, TTM or forward revenue?
How fast is revenue growing?
A multiple makes more sense when considered alongside growth.
What are the company’s profit margins?
Revenue quality matters.
Is the company generating cash?
Check operating and free cash flow.
How much debt does it have?
P/S doesn’t adequately capture leverage.
How does its P/S compare with similar companies?
Industry context matters.
How does today’s P/S compare with its own history?
Historical valuation can provide additional context.
What future growth is already reflected in the stock price?
This is especially important when P/S is unusually high.
If you cannot answer these questions, the P/S ratio alone probably isn’t enough to form a strong valuation conclusion.
P/S Ratio Example: Comparing Two Companies
Now consider two fictional companies.
| Metric | Company A | Company B |
|---|---|---|
| P/S | 2× | 6× |
| Revenue growth | 5% | 25% |
| Net margin | 3% | 20% |
| Debt | High | Low |
| Revenue quality | Mixed | Mostly recurring |
At first glance, Company A appears cheaper because its P/S is only 2× compared with Company B’s 6×.
But is Company A actually cheaper?
P/S alone cannot tell us.
Company B is growing five times faster, has a much higher net margin, lower debt and more recurring revenue.
The market may therefore be assigning Company B a higher multiple because investors expect substantially greater future earnings and cash flows.
This is exactly why “lower P/S = better investment” is an incomplete rule.
The correct approach is to understand the economics behind the multiple.
Can P/S Ratio Be Used to Find Undervalued Stocks?
P/S can help investors identify companies that trade at relatively low valuations compared with their revenue.
But that is not the same as proving that a stock is undervalued.
Consider the distinction:
Low P/S → Observation
Undervalued → Analytical conclusion
To conclude that a company may be undervalued, you need considerably more information.
You would want to examine:
- future revenue growth;
- margins;
- cash flow;
- debt;
- competitive position;
- industry conditions;
- management;
- capital allocation; and
- the assumptions embedded in the current share price.
Therefore, P/S is best viewed as a starting point for further research, not a standalone stock-picking formula.
P/S Ratio Formula: Quick Reference
The primary formula is:
P/S Ratio = Market Capitalization ÷ Revenue
The per-share version is:
P/S Ratio = Share Price ÷ Revenue Per Share
Where:
Revenue Per Share = Revenue ÷ Shares Outstanding
Quick interpretation
If a company has a P/S ratio of 3×, the market is valuing its equity at approximately ₹3 for every ₹1 of annual revenue.
Remember:
P/S measures valuation relative to sales—not profitability.
Frequently Asked Questions About P/S Ratio
What is a good P/S ratio?
There is no universal “good” P/S ratio. The appropriate multiple depends on the company’s industry, revenue growth, profit margins, financial risk, competitive position and future expectations.
A meaningful comparison is usually made against similar companies and the company’s own historical valuation.
Is a lower P/S ratio better?
Not necessarily.
A low P/S may indicate an attractive valuation, but it can also reflect declining revenue, weak margins, high debt or poor business prospects.
The ratio needs to be interpreted alongside fundamental data.
What does a P/S ratio of 1 mean?
A P/S ratio of 1× means the company’s market capitalization is approximately equal to its annual revenue.
It means investors are valuing ₹1 of annual revenue at approximately ₹1 of equity value.
It does not automatically mean the company is fairly valued.
What does a P/S ratio of 5 mean?
A P/S of 5× means investors are valuing the company’s equity at approximately ₹5 for every ₹1 of annual revenue.
Whether this is reasonable depends on growth, profitability and other fundamentals.
Why is P/S useful for loss-making companies?
Because P/S uses revenue rather than profit.
A company can have positive revenue while reporting negative earnings, making P/S potentially useful when a conventional P/E ratio isn’t meaningful. (Wall Street Prep)
What is the difference between P/S and P/E?
P/S compares market value with revenue, while P/E compares market value with earnings.
P/S is therefore less directly connected to profitability, while P/E incorporates profitability through its earnings denominator.
Is P/S better than P/E?
Neither is universally better.
P/S can be useful for loss-making or early-stage businesses, while P/E can be more informative for companies with stable and representative earnings.
Using both can provide a more complete picture.
What is a negative P/S ratio?
A conventional P/S ratio should not normally be negative because revenue is generally positive.
If a financial website shows a negative P/S, investigate the underlying data and calculation rather than assuming it represents a normal valuation condition.
Should I use TTM or annual revenue for P/S?
TTM revenue is often useful because it incorporates the most recent four quarters.
Annual revenue can also be appropriate, particularly when analyzing full-year results.
The most important point is to understand which period you’re using and keep the numerator and denominator conceptually consistent.
Can P/S ratio predict stock returns?
No.
P/S is a valuation metric, not a guaranteed return predictor.
A stock with a low P/S can continue falling, while a stock with a high P/S can continue rising if business performance and investor expectations remain strong.
Is P/S useful for Indian stocks?
Yes, particularly when comparing companies with similar business models and when earnings are negative or unusually volatile.
However, Indian investors should consider revenue growth, margins, cash flow, debt and industry-specific valuation measures alongside P/S.
What is the difference between P/S and EV/Sales?
P/S uses market capitalization, while EV/Sales uses enterprise value.
EV incorporates debt and cash, making EV/Sales particularly useful when comparing companies with different capital structures.
Final Takeaway: Use P/S as a Starting Point, Not a Verdict
The Price-to-Sales ratio is one of the easiest valuation metrics to understand:
P/S = Market Capitalization ÷ Revenue
It tells you how much investors are paying for each ₹1 of a company’s sales.
Its biggest advantage is that it can remain useful even when a company has negative or unusually volatile earnings. Its biggest weakness is that revenue alone doesn’t tell you whether a business is profitable, cash-generative or financially healthy. (Wall Street Prep)
That’s why a good P/S analysis should move beyond the ratio itself.
Think of the process as:
Revenue growth → Profit margins → Cash flow → Debt → Industry comparison → Historical valuation → Future expectations
A low P/S ratio can be interesting, but you need to understand why it is low.
A high P/S ratio can be justified, but you need to understand what future performance the market is already pricing in.
Most importantly, don’t treat P/S as a standalone buy or sell signal. Valuation multiples can remain elevated or depressed for long periods, and businesses can change in ways that historical ratios cannot predict.
Use the P/S ratio to ask better questions—not to replace fundamental analysis.
Educational disclaimer: This article is for educational and informational purposes only. It is not investment advice, a recommendation to buy or sell any security, or a promise of investment returns. Investors should conduct independent research and consider their financial circumstances and risk tolerance before making investment decisions.
Related Posts:
- Financial Ratios Explained: PE, PB, ROE & How to Analyze Any Stock
- What Is the Price-to-Book Ratio? Formula, Meaning & Examples
- P/E Ratio: Meaning, Formula, Examples & How to Analyze It
- What Is EBITDA? Meaning, Formula, Calculation & Examples
- P/E Ratio vs EV/EBITDA: Differences, Formulas & Examples
- What Is the PEG Ratio? Formula, Calculation, Meaning, and How to Use It
- What Is EPS? Earnings Per Share Explained With Formula, Examples & How to Analyze It
- How to Value a Stock: Complete Stock Valuation Guide

You may also like
What Is the Price-to-Book Ratio? Formula, Meaning & Examples
P/E Ratio vs EV/EBITDA: Differences, Formulas & Examples